

What Is a VSC? (And Should You Get One?)
Car repairs always seem to happen at the worst possible time. One minute your car is cruising along just fine, and the next—bam—your transmission gives out and so does your budget.
That’s where a Vehicle Service Contract (VSC) can help.
A VSC, sometimes called an extended warranty, is a protection plan that covers specific mechanical and electrical repairs after your manufacturer’s warranty expires. It’s not technically insurance—but it is a way to protect yourself from surprise repair costs.
Let’s break down what a VSC is, how it works, what’s covered (and what’s not), and whether it’s worth adding to your auto loan or refinance loan.
What Is a Vehicle Service Contract (VSC)?
A Vehicle Service Contract is an optional protection plan that helps cover the cost of certain repairs or part replacements due to mechanical breakdowns. It kicks in after your original manufacturer’s warranty ends—or sometimes, even overlaps with it to provide additional coverage.
Unlike auto insurance, which protects against accidents or theft, a VSC is all about helping with unexpected repair bills due to wear, tear, or system failures.
What Does a VSC Cover?
Coverage varies depending on the plan, but a typical VSC may include:
- Engine and transmission repairs
- Heating and air conditioning systems
- Electrical components
- Fuel systems
- Suspension and steering
- Some plans include extras like roadside assistance, rental car reimbursement, or trip interruption coverage
Some VSCs are exclusionary (they cover everything except what’s listed), while others are component-based, only covering specific parts.
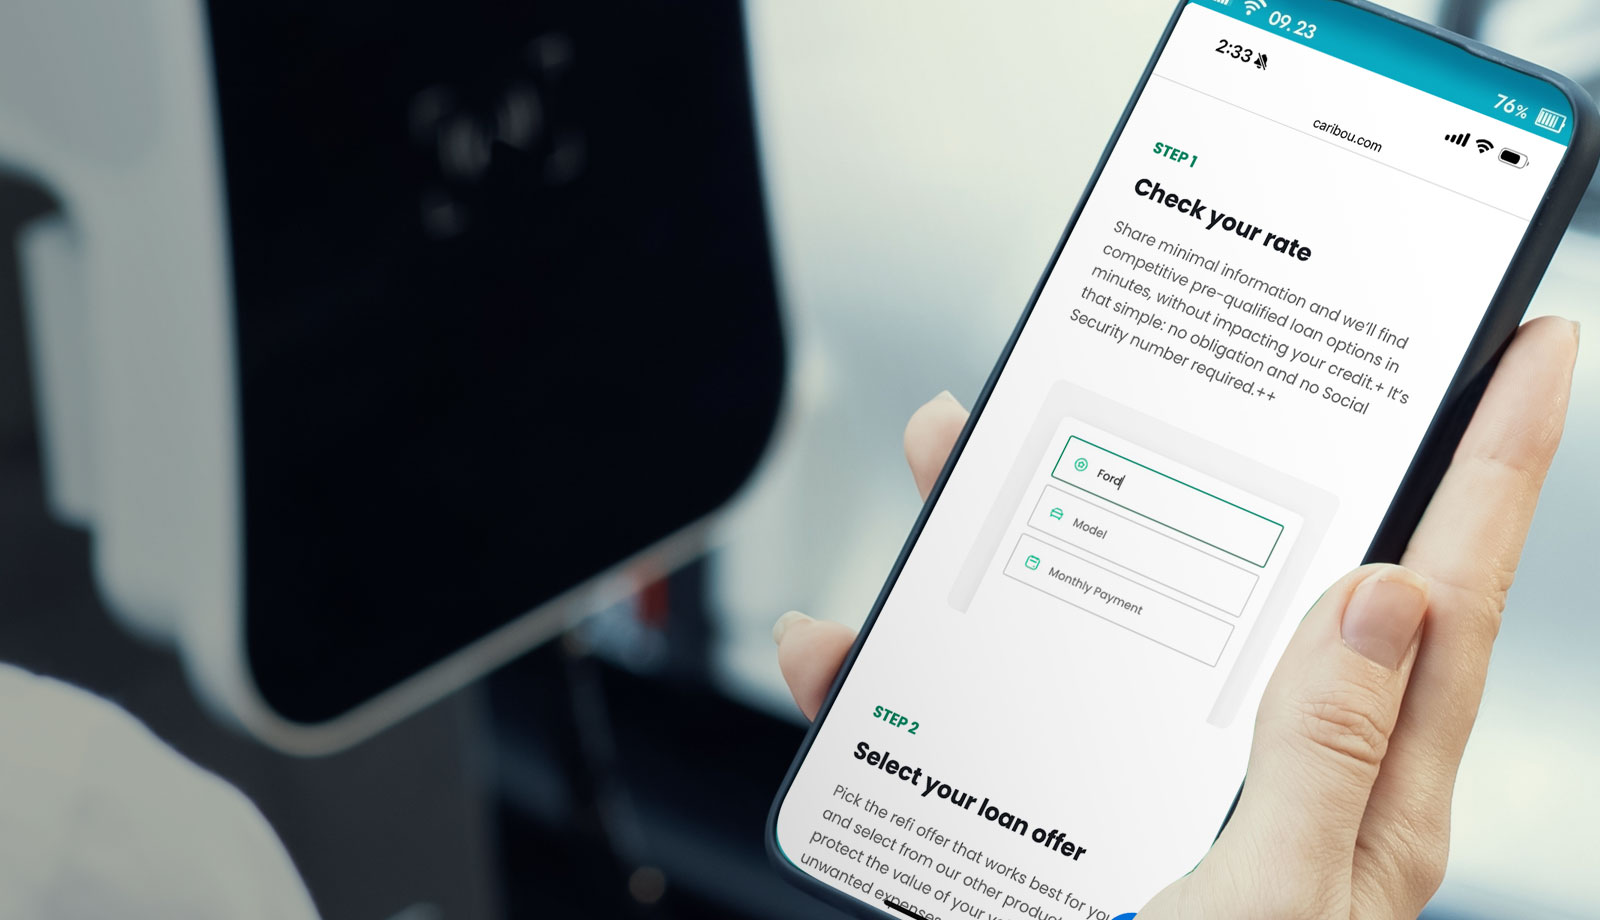
TIP CORNER:
Sites like Caribou make it easy to compare auto loan refinance offers from multiple lenders in one place.
What’s Not Covered?
VSCs do not typically cover:
- Routine maintenance (like oil changes or tire rotations)
- Damage from accidents or weather (that’s your auto insurance)
- Wear-and-tear items like brake pads or windshield wipers
- Modifications or aftermarket parts
- Cosmetic damage or interior wear
It’s important to read the fine print and understand exactly what is—and isn’t—included.
Who Should Consider a VSC?
A VSC can offer peace of mind, but it’s not for everyone. It may be a smart move if:
- Your car is no longer under the original manufacturer warranty
- You drive an older vehicle with high mileage
- You plan to keep your car for several more years
- You’re not financially prepared for a major repair
- You’re financing or refinancing your car and want to roll VSC costs into the loan term
If you’ve recently gone through an auto loan refinance, a VSC can also be a smart way to protect your newly adjusted investment.
Where Can You Buy a VSC?
You can purchase a Vehicle Service Contract through:
- Your car dealership (often at the time of sale)
- A third-party provider or financial institution
- A lender or lending marketplace like Caribou, especially during refinancing
Just be sure to research the provider’s customer service, coverage transparency, and claims process before you commit.
Can You Add a VSC to a Refinance Loan?
Yes! Many drivers choose to add VSC coverage when they refinance their auto loan. Rolling the VSC cost into your new loan term can help you avoid upfront expenses while gaining long-term protection.
Just be sure to review how this affects your monthly payment and overall cost of the loan—especially if you’re extending the term.
Protection That Goes the Extra Mile
Car repairs are a fact of life—but big repair bills don’t have to be. A Vehicle Service Contract gives you added security and budgeting predictability, especially if your vehicle is out of warranty or your finances can’t absorb a surprise $2,000 repair.Whether you’re buying, financing, or refinancing, adding a VSC is one way to drive forward with extra peace of mind.


